You rent cars to gig drivers. Uber. Lyft. DoorDash.
Your cars are cheap. Most cost around $5,000. Some less.
So why are you paying full coverage prices to protect them?
Here’s the smarter move: skip collision. Keep liability. Let your rental agreement cover the rest.
This guide breaks down exactly why – and where liability-only can go wrong if you get it too thin.
Got 20 cars or fewer? SoftCar is 100% free for you. Book a free demo →
Your Car Is Cheap. That Changes the Math.
Collision coverage protects your car. But think about what your car is actually worth.
A beat-up Corolla or Civic in a gig fleet runs about $5,000. Maybe $8,000 if it’s newer.
Paying an extra $21 a day for collision coverage to protect a $5,000 asset doesn’t add up. Do the math over a year – that’s over $7,500 in premiums to protect a car worth less than that.
Smart fleet owners handle this differently:
- Put it in the rental agreement: if the renter damages the car, the renter pays for it
- Back it with a security deposit
- Have them sign a digital agreement before they get the keys
Now the car is covered – without you paying for collision every single day.
But Here’s Where It Gets Dangerous
Your renter’s damage isn’t the risk that ends your business. Someone else’s car is.
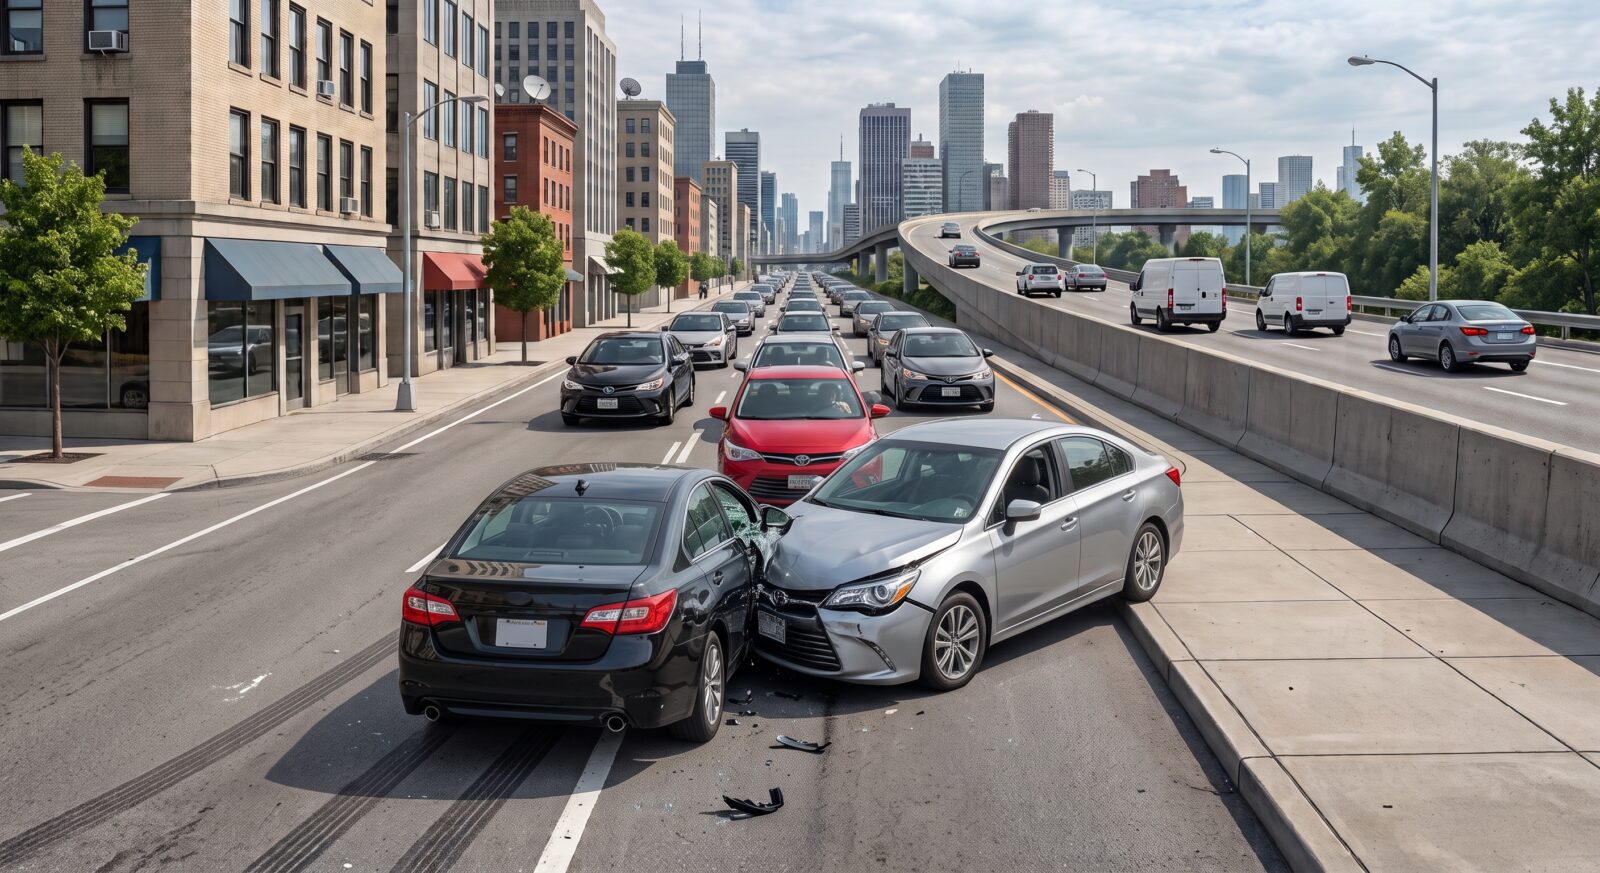
Picture this: your renter is rushing to a drop-off and rear-ends a BMW at a red light. That BMW is worth $80,000.
Your $5,000 rental car and a renter-pays-for-damage clause don’t help you here. That BMW belongs to someone else. Their insurance company – and their lawyer – is coming after whoever has the money. That’s the fleet owner. That’s you.
This is exactly what liability coverage is for. It’s not there to fix your car. It’s there to pay for the other person’s car – and it’s the only thing standing between one bad afternoon and a lawsuit that outlasts your business.
The Part That Costs Even More: Hospital Bills
Car damage has a ceiling. A vehicle can only be worth so much.
A person’s hospital bill does not have a ceiling.
If anyone gets hurt in a crash – the renter, the other driver, someone walking by – the bills add up fast:
- One night in the hospital: thousands of dollars
- Surgery: tens of thousands
- Weeks of recovery: hundreds of thousands
- Long-term injury care: $1 million or more
This is the real reason to never go liability-only with weak limits, and never skip liability altogether. Skipping collision on a $5,000 car is smart. Skipping or underbuying liability is how fleets go under.
What $21 a Day Actually Buys You
SoftCar gives you on-rent liability coverage for about $21 a day, with protection up to $110,000 through certified insurance providers.
Here’s the trade-off, side by side:
| What happens | No liability coverage | Renter-pays clause only | SoftCar Liability |
| Renter dings your $5,000 car | You’re out the repair cost | Renter pays it – problem solved | Renter pays it – problem solved |
| Renter hits an $80,000 BMW | You pay out of pocket | You still pay – renter can’t cover it | Covered up to $110,000 |
| Someone gets hurt | You face hospital bills and lawyers | You face hospital bills and lawyers | The policy steps in, up to its limits |
| Car goes out on rent | You hope the paperwork is done | Depends on your contract | Coverage turns on automatically, every trip |
Notice the pattern: a renter-pays clause protects your car. Liability protects everything and everyone else. You need both – you just don’t need to pay for collision on top of liability to get full protection.
How to Set This Up the Smart Way
This is the setup experienced fleet owners use to stop overpaying:
- Skip collision on low-value cars – if the car is worth $5,000–$8,000, self-insure it through your contract instead of paying daily premiums for it
- Make the renter pay for car damage – the deductible, and anything not covered, goes to them, in writing
- Back it with a security deposit – hold real money before the car goes out
- Never skip or underbuy liability – this is the one coverage you cannot shift onto the renter, because it protects other people’s property and other people’s bodies
- Use digital agreements – signed before they get the keys, every time
Get this balance right and you stop bleeding money on collision premiums for cars that aren’t worth insuring that way, while staying fully covered for the crash that could actually end your business.
Why Cheap “Liability-Only” Plans Are Still a Trap
Not all liability-only coverage is equal. Some platforms sell liability-only cheap by quietly cutting corners:
- Lower limits – $30,000 of coverage disappears fast when hospital bills start at $80,000
- Bigger deductibles – you save $5 a day, then owe $5,000 the first time something happens
- Strict driver rules – some platforms keep prices low by rejecting the gig drivers you actually rent to
Gig drivers also cost more to insure than average – they drive more miles, in more traffic, on tighter schedules. That’s not a reason to skip liability. It’s a reason to make sure your liability limits are actually high enough to matter.
Don’t compare price per day. Compare the limit against what a real BMW-and-a-hospital-bill scenario would cost you.
Free If You Have Under 20 Cars
Here’s the best part.
SoftCar is 100% free for fleets with fewer than 20 cars.
No setup fees. No commissions. Nothing.
You get bookings, payments, renter screening, digital contracts, and your own booking website – free. You only start paying when your fleet grows past 20 cars.
We’re willing to grow with you. Start free. Pay later, when you’re bigger.
Free from day one:
- Your own booking page – take rentals 24/7, keep every dollar
- Driver screening – check licenses before the keys change hands
- Digital contracts – signed and saved, every time, including your renter-pays-for-damage clause
- One dashboard – all your cars, renters, and payments in one place
- Liability insurance from $21/day – turns on with every trip
Questions People Ask
Do I need collision insurance for a rideshare fleet? Not always. If your cars are low-value (around $5,000–$8,000), many fleet owners skip collision and instead require the renter to pay for any damage in the rental agreement. Liability coverage is the one you should never skip.
How much does liability-only insurance cost for a gig fleet? About $21 a day, with up to $110,000 in coverage through SoftCar’s certified insurance providers.
What if my renter hits an expensive car? This is exactly what liability coverage is for. It pays for damage to someone else’s vehicle, up to your policy limit – something a renter-pays clause on your own car can’t do for you.
How much are hospital bills after a car crash? They start around $200,000 for serious injuries and can pass $1 million for severe ones. This is why liability limits matter more than saving a few dollars a day.
Is SoftCar really free? Yes. Under 20 cars, you pay nothing. The full platform is free until you grow past 20 vehicles.
Can I make the renter pay for damage to my car? Yes. Set your rental terms so the driver pays the deductible and covers damage to your vehicle. A security deposit and signed digital contract make it enforceable.
Small Gig Fleet? Stop Overpaying for Coverage You Don’t Need.
20 cars or fewer? Start free today. No setup fees. No commissions. Full platform.
Book a free 30-minute demo → and see how easy fleet life can be.
